IRS Releases 2027 Contribution Limits, With Few Surprises
The Internal Revenue Service (IRS) has announced the 2027 contribution and benefit limits for qualified plans – and many of the limits will increase next year.[i]
The Baseline
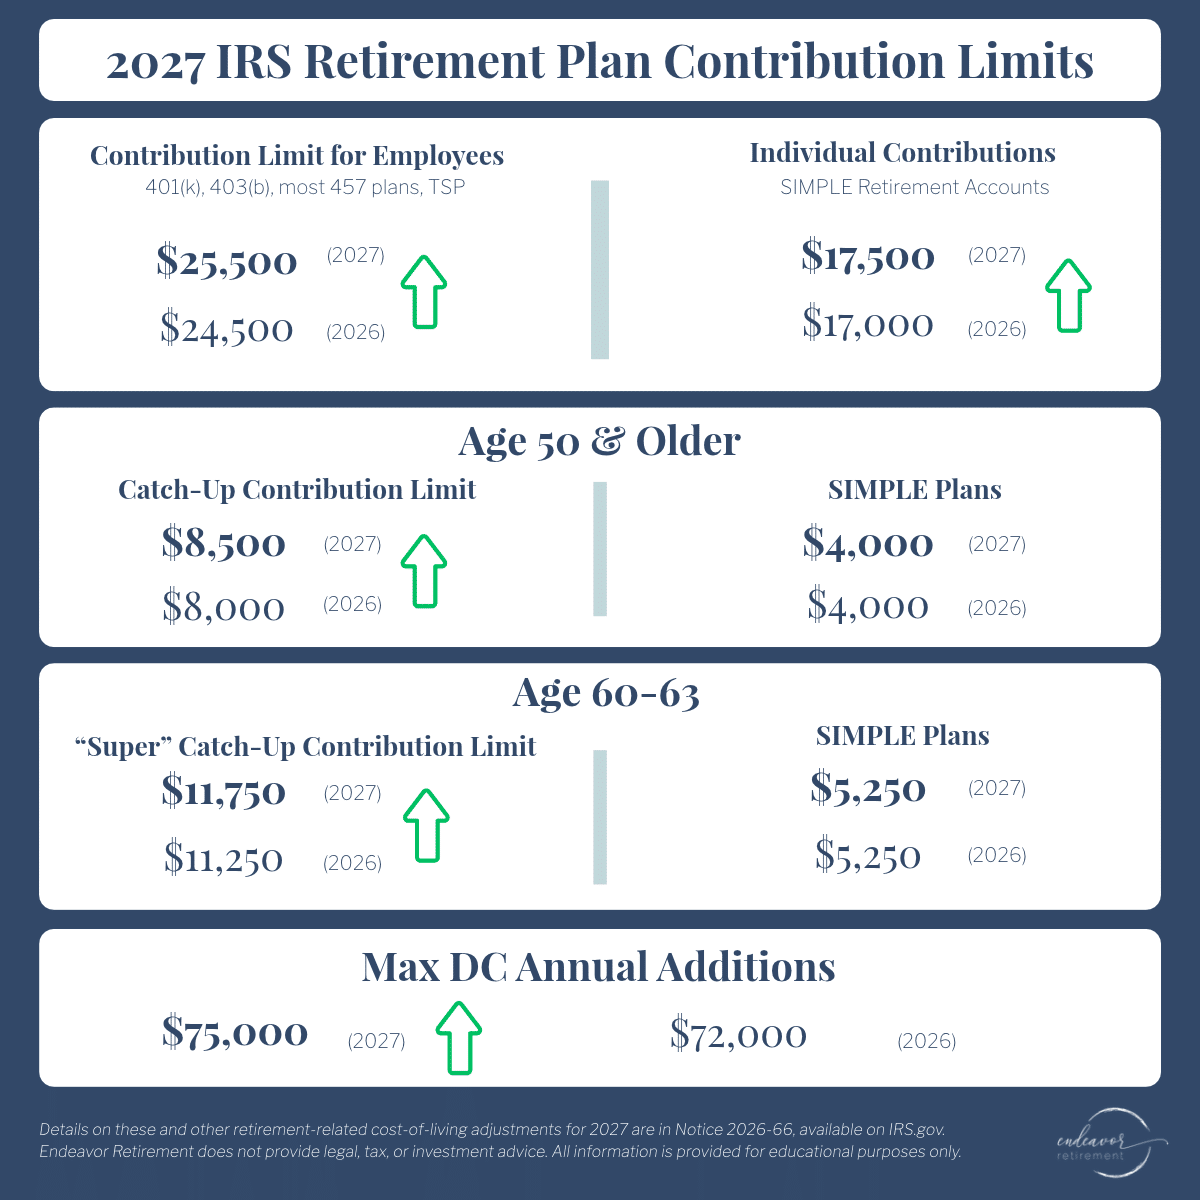
Pre-Tax Deferrals: The annual contribution limit for employees who participate in 401(k), 403(b), governmental 457 plans and the federal government’s Thrift Savings Plan is increased to $25,500, up from $24,500 for 2026.
Catch-Up: The catch-up contribution limit that generally applies for employees aged 50 and over who participate in most 401(k), 403(b), governmental 457 plans and the federal government’s Thrift Savings Plan is increased to $8,500, up from $8,000 in 2026.
SIMPLE: The limitation under section 408(p)(2)(E)(i)(III) that generally applies to salary reduction contributions under a SIMPLE retirement account or elective contributions under a SIMPLE 401(k) plan is increased from $17,000 in 2026 to $17,500 in 2027.
SECURE 2.0-Related Adjustments
Super Catch-Up: Under a change made in SECURE 2.0, a higher catch-up contribution limit applies for employees aged 60, 61, 62 and 63 who participate in these plans. For 2027, this higher catch-up contribution limit rises to $11,750 from $11,250 in 2026.
Pension-Linked Emergency Savings Accounts (PLESA): The limitation under section 402A(e)(3)(A)(i) concerning pension-linked emergency savings accounts that may be included in certain types of defined contribution plans is increased from $2,600 to $2,700.
Distributions Related to Domestic Abuse: The limitation under section 72(t)(2)(K)(ii)(I) for eligible distributions to victims of domestic abuse from applicable eligible retirement plans is increased from $10,500 to $10,900.
Other Limit Definitions
Highly Compensated: The threshold used in the definition of “highly compensated employee” under section 414(q)(1)(B) is increased from $160,000 to $170,000 (it was unchanged at $160,000 in 2026). The threshold under section 416(i)(1)(A)(i) concerning the definition of “key employee” for top-heavy plan purposes is increased from $235,000 to $245,000.
Maximum contribution limit (415(c)): The limitation for defined contribution plans under section 415(c)(1)(A) is increased in 2027 from $72,000 to $75,000.
What’s Left Unchanged
IRA Contributions: The limit on annual contributions to an IRA remains at $7,500. The IRA catch‑up contribution limit for individuals aged 50 and over was amended under the SECURE 2.0 Act of 2022 (SECURE 2.0) to include an annual cost‑of‑living adjustment also remains at $1,100.
Other Unchanged Limits
|
Item |
Amount |
|
SIMPLE catch-up, generally age 50 and older |
$4,000 |
|
SIMPLE catch-up, ages 60–63 |
$5,250 |
|
Catch-up for certain SIMPLE plans under §414(v)(2)(B)(iii), generally age 50 and older |
$3,850 |
|
Age-50 catch-up for starter 401(k)s and deferral-only safe harbor 403(b)s |
$1,100 |
|
SEP minimum compensation threshold |
$800 |
|
Annual limit on length-of-service awards for eligible volunteers |
$8,000 |
|
Limit on qualified gratuitous transfers of employer securities to an ESOP |
$65,000 |
|
Compensation threshold for excluding employees from the employer-contribution portion of the small-plan startup credit |
$110,000 |
|
Traditional IRA deduction phase-out for married filing separately, where the filer is covered by a workplace plan |
$0–$10,000 |
|
Roth IRA contribution phase-out for married filing separately |
$0–$10,000 |
[i] Internal Revenue Service, 2027 Amounts Relating to Retirement Plans and IRAs, as Adjusted for Changes in Cost-of-Living, Notice 2026-66 (Washington, DC: Internal Revenue Service, 2026), https://www.irs.gov/pub/irs-drop/n-26-66.pdf.
Endeavor Retirement does not provide legal, tax, or investment advice. All information is provided for educational purposes only.